In 2014 Social Herds examined New Zealand’s housing problems. The evidence showed:
- falling homeownership
- house prices rising faster than incomes
- housing shortages
- unequal housing outcomes for Māori and Pacific peoples.
In 2018 a government stocktake raised many of the same concerns.
More than a decade after our original analysis, New Zealand media is still writing about housing problems. Housing ranked fifth by headline count across the period covered by our report. So what are the current problems, and how have they changed?
Where housing has improved – and where pressures remain?
Some housing measures have improved. Homeownership has edged up, house prices and mortgage rates have eased, and recorded emergency-housing use has fallen. But those changes have not benefited everyone equally, and a fall in emergency-housing use does not tell us whether wider homelessness has fallen.
The figures below show the pressures that remain.
14.6× income
Buying remains out of reach
The median home costs 14.6 times median disposable household income.
46% of renters
Housing absorbs too much income
Nearly half spend at least 30% of their disposable income on housing.
112,496 people
Homelessness is wider than emergency housing
This was the number experiencing severe housing deprivation in 2023.
Unequal outcomes
Māori and Pacific people are hardest hit
Severe housing deprivation affected 228 people per 10,000 nationally, compared with 394 Māori and 657 Pacific people.
New builds
Housing availability
It is difficult to establish how many approved homes have actually been completed. Stats NZ’s follow-up of one group of consented homes found that 87.5% had received a code compliance certificate three years later—showing the gap between consent and completion.
2026 New Zealand Housing Report Summary - as told by the NZ media
Current issues include:
Fast-track approvals: who delivers the infrastructure?
Central government can accelerate approvals, while councils face responsibility for roads, water and other services. Does approval resolve the delivery problem—or leave funding and accountability unsettled?
Kāinga Ora: from review to results
The review brought scrutiny of costs, leadership and delivery. How much does subsequent coverage tell us about improved performance and homes reaching people who need them?
Building standards: affordability, quality and risk
Efforts to build faster and more cheaply raise questions about durability, safety and long-term costs. Who benefits from changes to standards, and who carries the risk?
The housing market: does supply meet need?
More development does not automatically provide homes in the right places, at prices households can afford. How well does the market connect commercial opportunities with housing need?
What the figures do—and do not—show
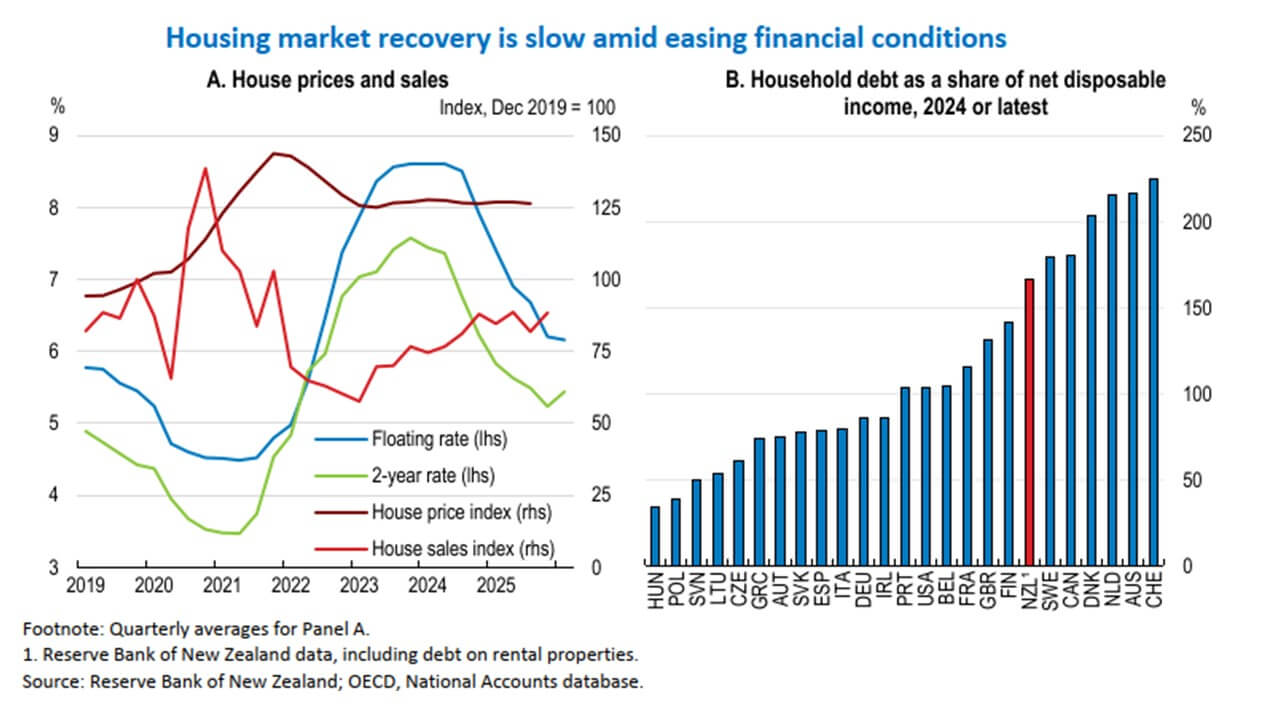
Homeownership and some measures of affordability have improved, but the gains are uneven. A median-priced home remains beyond the reach of many households, and housing costs still take a large share of renters’ incomes.
The fall in emergency-housing use needs careful interpretation. The 2023 Census measure of severe housing deprivation includes people living without shelter, in temporary accommodation, sharing because they have nowhere else to live, or in an uninhabitable home. A smaller emergency-housing caseload does not, by itself, show that these wider needs have fallen.
More building is part of the answer, but the nearly 40,000 homes consented in the year to May 2026 are not yet completed homes. National totals also cannot tell us whether new homes are affordable, suitable and located where people need them.
Housing case studies 2026
From housing promises to homes people can use
A rezoned site, approval and consent are steps towards housing—not homes people can live in. To judge progress, we need to know whether infrastructure is funded, construction is completed, and the resulting homes are affordable and suitable for the people who need them.
Delmore (near Ōrewa) illustrates the infrastructure question in practice. Its fast-track approval was reported alongside a proposal to truck wastewater while servicing was resolved. The test is what permanent solution will be delivered, who will pay for it, and when.
Queenstown
Queenstown has major housing developments under consideration while local workers struggle to find secure, affordable accommodation. More homes will help only if their price, type and location match the need.
Social housing
In May 2024, the Government announced funding for 1,500 additional social homes across New Zealand through community housing providers, using savings from ending the First Home Grant. Delivery was planned over July 2025–June 2027. The official government August 2026 dashboard recorded 353 homes built and available for tenanting, with a further 995 under construction and 206 approved at the planning stage. These figures distinguish announced funding from homes people can actually move into.
For any housing policy or strategy, the neglected questions appear to be:
- How many homes will be completed and occupied, where and by when?
- Who will be able to afford them?
- Who will fund the roads, water and other services? and
- Who is accountable if the promised homes do not arrive?
Political parties’ housing policies - as at 26 September 2026
| Party | Main approach | Specific commitments | What remains unclear |
| National | Increase supply through planning reform, infrastructure financing and targeted housing investment | Free more land for development; finance infrastructure through property levies and other tools; incentivise councils; fund social and affordable rentals through the Flexible Fund | How many net additional affordable and social homes will result; what households will pay; whether infrastructure and ratepayer risks are fully covered |
| Labour | Restart public-house construction and improve financing for community housing | $2.9 billion for Kāinga Ora construction; $745 million in operating support; a $950 million guarantee to reduce community-provider borrowing costs; tax changes intended to discourage property speculation | The number, type and location of net additional homes; infrastructure requirements; detailed renter and first-home-buyer policies |
| Greens | Expand public housing, strengthen renters’ rights and address homelessness directly | Build 35,000 public homes over five years; cap annual rent increases at 2%; restore protection from no-cause eviction; introduce a rental warrant of fitness; reverse emergency-housing restrictions | Detailed construction capacity, regional allocation, infrastructure requirements and the complete cost and delivery programme |
| ACT | Liberalise planning and construction while changing how infrastructure is funded | More permissive property and planning rules; alternative consenting and construction arrangements; infrastructure contributions from growth, including a proposed temporary-worker levy | How the approach would address homelessness, social housing and low-income renters; how building quality, liability and affordability would be protected |
| New Zealand First | No complete current housing approach identified | The party’s 2026 policy page does not yet contain a detailed housing package | Its position on affordability, renters, homeownership, social housing, infrastructure, funding and delivery |
| Opportunity | Reduce land speculation and encourage a large increase in construction | Introduce a land-value tax; simplify zoning; support offsite construction; underwrite qualifying affordable developments; return some construction GST to councils | Detailed costs and timetable; the number and location of homes; provisions for renters, homelessness and social housing; how affordability would be maintained |
Historical Information and Data
Historical baseline: what the evidence showed in 2018 and 2014

It seems to have become accepted (in the US) that a median multiple of 3.0 times (your income) or less is a good marker for housing affordability. The median multiple for New Zealander’s is closer to 4.5.
http://www.interest.co.nz/property/house-price-income-multiples
There is on-going discussion as to what the figure is for NZ and whether methodology used by other countries is relevant to NZ’s situation.
Additional information on the NZ property market is available from from Quotable Value
For those who want more information on the cost of a NZ home should listen to the interview on radionz with Jonno Ingerson titled “Auckland property prices up 33% in 3 years”.
Homeownership Issues in Main Centres
- 2017 the lowest homeownership rates
- Increasing house prices:
- 30% (nationwide) house price inflation whilst incomes rose by about 15%
- House pricing increased more in Auckland and the Waikato 65 and 45% respectively
- Reserve Bank policies require lower loan-to-value ratios
- Lack of new houses with Auckland’s population growing by 40,000 per year
- Housing shortage estimated at between 28-45K houses
Rental Issues
- The decreasing number of properties available
- high cost of new builds – impacting on rental return
- Rental costs outstripping income (in some areas rents have increased 2x as fast as incomes)
- Lack of long term tenancies and no protection against frequent rental increases
- Rental tenants generally pay a much higher proportion of their disposable household on accommodation than owner-occupiers or social housing tenants
Maori and Pacific People
- 2013 28% of Maori and 19% of Pacific People were homeowners compared to 57% of Europeans
- 1986 approximately 50% of Maori children lived in their own home in 2013 this dropped to 39%
- 1986 approximately 50% of Pacific children lived in their own home in 2013 this dropped to 28%
- 1986 -2013 Pacific People’s homeownership dropped from 56 to 27%
Effect of housing costs on disposable income


Disposal income (RGNDI) defined:- measures the purchasing power of New Zealanders. Higher RGNDI per person shows that a nation has a greater capacity to deliver a better quality of life and standard of living to the population.
RGNDI measures the total income, adjusted for inflation, that New Zealand residents receive, not only from domestic production but also from the net income flows with the rest of the world.


The median income in NZ: 2011
The average household income is almost 2x the median income
New Zealand Income Survey – June 2013 Quarter
Based on the information below the median income is approximately $43,000 -45,000 per annum
Between the June 2012 and June 2013 quarters:
- Median weekly income from wages and salaries (for those receiving income from this source) was $844, up $38 (4.8 percent).
- Median hourly earnings were $21.58, up 72 cents (3.5 percent).
- Median weekly income for all people from all sources was $575.
- The proportion of people aged 15–24 years earning wage and salary income was down 0.7 percentage points to 15.6 percent.
- The proportion of people aged 50 years and over (50+) earning wage and salary income was up 1.3 percentage points to 31.0 percent.
The average household income is seen as a less reliable indicator of income than the median wage or median hourly rate
Visit Child wellbeing and Health page for effects on low incomes on child health
Visit the Equality page to find out more about the difference between incomes levels in NZ
(i) Household income: Between the years ending 30 June 2010 and 30 June 2013, average annual household income from:
- all regular sources rose – from $76,733 to $85,588 (up 11.5 percent)
- wages and salaries rose – from $75,526 to $84,462 (up 11.8 percent)
- New Zealand Superannuation and war pensions rose – from $20,652 to $22,380 (up 8.4 percent).
(ii) Household expenditure: Between the years ending 30 June 2010 and 30 June 2013:
- average weekly household expenditure increased by 9.1 percent – from $1,019 to $1,111
- the largest changes in average weekly household expenditure were on transport (up $27 to $158),
- food (up $15 to $193), and housing and household utilities (up $21 to $273)
- average weekly rent payments increased by $32 – to $275
Cost of renting is high

In 2012/13,
- 35.5 percent of households that did not own their dwelling spent more than 30 percent of their household income on their housing costs,
- 23.1 percent spending more than 40 percent.
In contrast
- 11.9 percent of those who owned, or partly owned, their dwelling spent30 percent or more of their household income on housing costs, and
- 5.6 percent spent 40 percent or more.